Mortgage automation trends are changing a core lending question: not simply how quickly can a file move, but how early can a lender identify the right reason to start a conversation? Faster underwriting, document collection, and status updates matter. But for growth teams, the greater advantage is upstream - recognizing meaningful borrower, property, and market events before they become obvious to every competitor.
Automation has moved beyond task reduction. It is becoming a way to direct human attention toward the loans, referral relationships, properties, and borrowers most likely to warrant action. The firms that benefit will not be those that automate the most activity. They will be those that use automation to distinguish a real opportunity from another record in a crowded system.
Mortgage Automation Trends Are Moving Upstream
For years, mortgage technology investment centered on processing. Lenders automated application intake, pricing, disclosures, income verification, document classification, conditions, and borrower notifications. Those improvements remain necessary. They reduce cycle times, lower operational friction, and give loan teams more capacity when volume returns.
The next shift is earlier in the lifecycle. Revenue teams are applying automation to market observation, lead routing, relationship management, and next-best-action decisions. Rather than waiting for a consumer to complete a form or contact a lender, they are looking for lawful, relevant signals that may indicate a lending need, a property transition, or a change in financial circumstances worth understanding.
This distinction matters because automation at the fulfillment stage improves efficiency after demand arrives. Automation at the intelligence stage can improve the quality and timing of demand creation. A lender may process a purchase application more efficiently than last year and still lose market share if competitors identify emerging opportunities first.
Signal Collection Is Replacing List Acquisition
Generic lead lists have a familiar weakness: they treat records as if they carry the same commercial value. They do not. A name, address, and phone number say little about urgency, fit, recency, or the reason outreach may be relevant.
Modern mortgage automation is increasingly built around event-driven intelligence. Public filings, property transfers, lien activity, ownership changes, listing events, investor activity, and other record-based indicators can provide a clearer view of changing market conditions. Individually, many signals are incomplete. Combined with timing, property context, and existing relationship data, they can become a more credible basis for prioritization.
That does not mean every event should trigger a call. It means automation should identify the events that deserve review, enrich them with context, and route them to the appropriate team or workflow. The goal is not more outreach. It is better-directed outreach.
The Operational Trends That Matter Most
The most consequential developments are practical. They affect how a lender allocates staff time, manages response windows, and decides which prospects deserve immediate attention.
AI Is Becoming a Triage Layer, Not a Substitute for Judgment
Artificial intelligence is being used to classify documents, summarize loan notes, extract data, draft communications, and identify workflow exceptions. Those are useful applications, particularly where teams are managing high file volumes.
Its more strategic role is triage. AI can help assess large volumes of signals and records against defined criteria, then surface the cases that align with a lender's products, geography, referral strategy, or risk tolerance. This is especially valuable when raw data is abundant but attention is limited.
The trade-off is clear. Models can accelerate prioritization, but they should not be trusted as an unexamined decision-maker. A score without source context can create false confidence. Teams need to know what event occurred, why it was ranked, how recent it is, and what action the signal is intended to support. Human review remains essential where relevance, consumer impact, or compliance judgment is involved.
Workflow Automation Is Becoming More Selective
Earlier automation programs often focused on moving every lead through the same sequence. A new contact entered the CRM, received an email, was assigned a task, and entered a cadence. That approach creates activity, but not necessarily opportunity.
More mature teams use rules and intelligence to vary the workflow. A high-confidence, time-sensitive property event may require same-day review by an originator or acquisition specialist. A lower-confidence signal may enter a research queue. An existing past client with a relevant trigger may be routed to the relationship owner rather than a general call pool.
Selective automation protects team capacity. It also produces better customer experiences because outreach can be informed by a legitimate business reason instead of a generic script. Timing is part of relevance. So is restraint.
Data Enrichment Is Becoming a Revenue Requirement
A public record alone rarely tells the full story. A recorded document may indicate an event, but it does not automatically explain ownership structure, property characteristics, transaction history, likely financing relevance, or whether the record fits a team's territory and strategy.
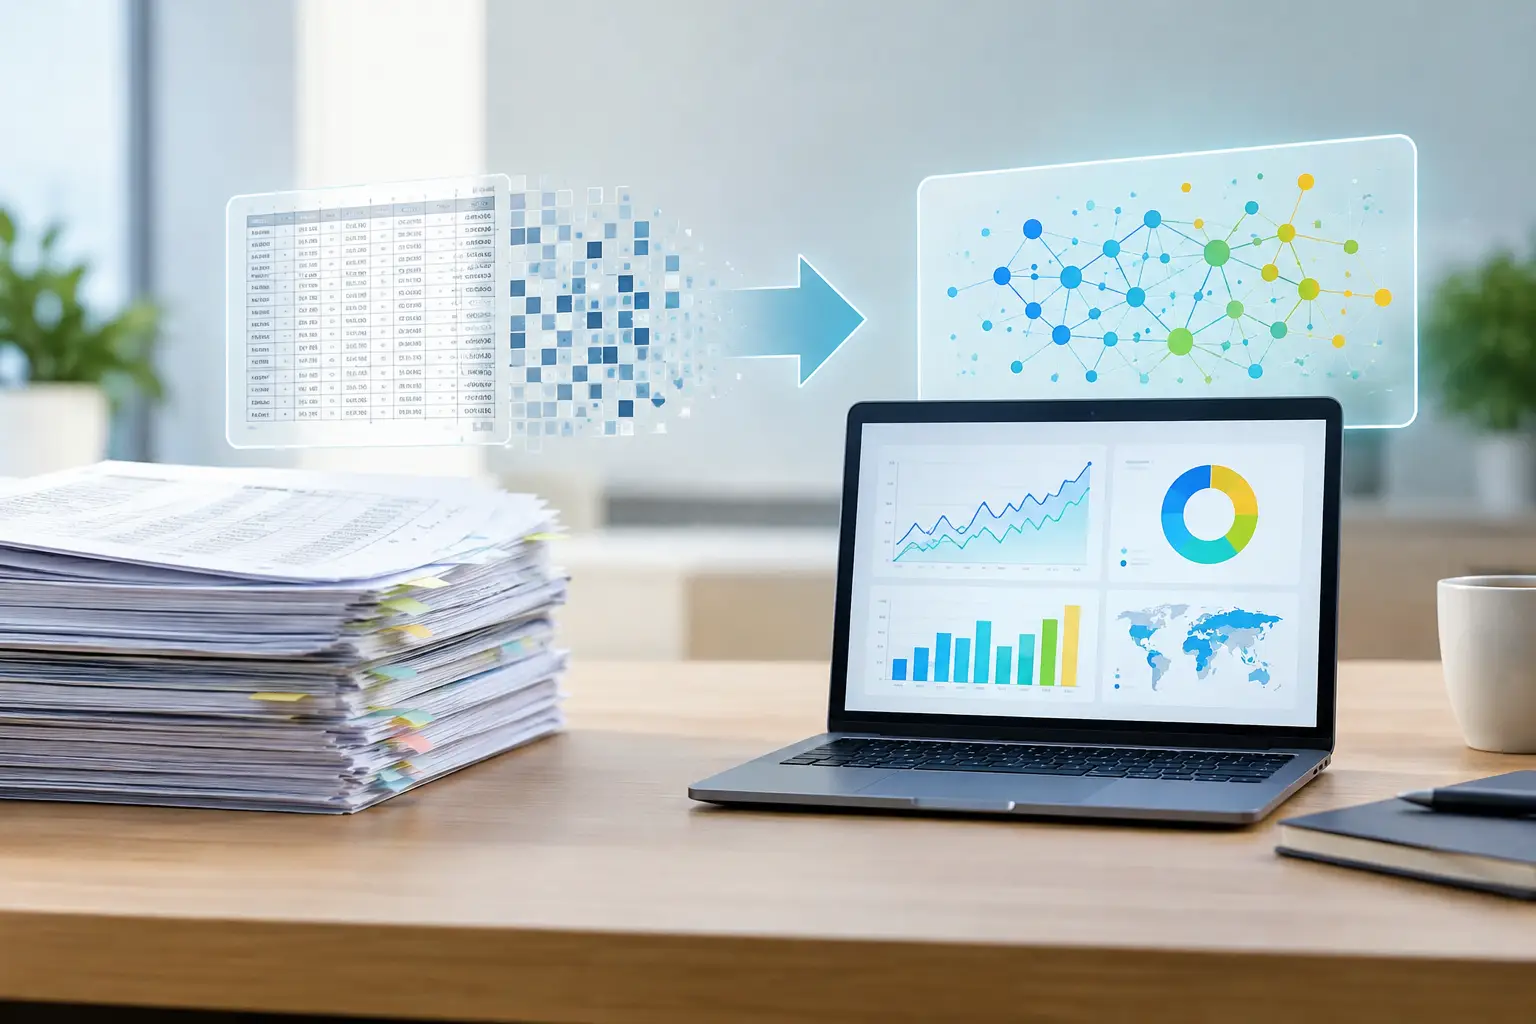
This is why enrichment and entity resolution are becoming central to mortgage automation trends. Systems must connect fragmented records, reduce duplication, organize events chronologically, and add the context necessary for a professional to make a decision. The value is not in collecting more files. It is in making the signal usable.
For mortgage leaders, that changes the evaluation standard for technology. Ask whether a platform produces a larger database or whether it shortens the distance between an external event and a defensible next action. Those are not the same outcome.
The New Competitive Window Is Between Event and Awareness
The traditional mortgage funnel begins when a consumer raises a hand. The emerging model begins earlier, when a meaningful event occurs and a lender has enough context to determine whether engagement is appropriate.
That window can be short. As signals become widely available through consumer portals, broad lead marketplaces, and public search tools, the first responder advantage weakens. The more valuable position is to recognize the event early, interpret it correctly, and assign it before the market treats it as common knowledge.
This is where the progression from Deal Pulse to Intelligence to Opportunity becomes operationally useful. Deal Pulse captures the event. Intelligence explains its context and relevance. Opportunity directs the next action. VORTOC is built around that progression because raw public-record data is not a growth strategy on its own. The event others overlook only becomes valuable when a team can understand and act on it.
Compliance Must Be Designed Into the Automation
More automated outreach creates more compliance exposure when teams treat data availability as permission to contact a consumer in any manner. Public records can support lawful business intelligence, but they do not remove obligations under federal, state, and local rules, internal policies, licensing requirements, or communication preferences.
Compliance should be part of the workflow design, not a review step added after deployment. That includes maintaining accurate contact permissions and suppression processes, following applicable calling and texting rules, documenting source information where required, controlling user access, and establishing clear procedures for disputed or inaccurate records.
It also requires care with automated scoring. Teams should avoid using models in ways that create prohibited discrimination, make unsupported assumptions about consumers, or obscure the basis for a decision. Automation can prioritize work. Accountability still belongs to the lender, originator, investor, or operator using it.
What Mortgage Leaders Should Build Next
A practical automation strategy starts with a narrow commercial question. Which events would create an actionable advantage if your team saw them earlier? The answer may differ for a retail lender rebuilding purchase volume, a correspondent lender seeking referral growth, or an investment group monitoring financing and property transitions.
Then define the action before adding more data. Who reviews the signal? How quickly? What context do they need? Which conditions make it high priority? What happens if the signal is incomplete, duplicated, stale, or inappropriate for outreach? Clear operating rules prevent intelligence from becoming another unattended dashboard.
Finally, measure more than lead volume. Track speed from signal to review, percentage of prioritized records accepted by users, contact quality, appointment rates, conversion by signal type, and the staff time required to produce each opportunity. If automation generates more tasks but fewer meaningful conversations, it is not creating leverage.
The strongest mortgage organizations will not treat automation as a replacement for local knowledge, lender judgment, or trusted relationships. They will use it to protect those advantages - placing the right event in front of the right professional while there is still time to matter.