A borrower rarely wakes up looking for a lender without a reason. A rate change, a new property search, an approaching maturity date, a life event, or a shift in equity can create that reason. The question is not simply when should lenders contact borrowers. It is whether the lender has enough context to make the outreach relevant, useful, and compliant.
For mortgage teams, timing is an advantage only when it is paired with judgment. Contact too early and the message feels speculative. Contact too late and the borrower has already chosen a competitor. The strongest outreach begins when a meaningful event is visible, the potential need is credible, and the lender can offer a clear next step.
When Should Lenders Contact Borrowers?
Lenders should contact borrowers when a verified signal suggests a financing need or a material change in the borrower’s situation, and when outreach can be made through a lawful, appropriate channel. The signal itself is not the opportunity. It is the starting point for qualification.
A public-record event may indicate a new purchase, a transferred title, a recorded loan, an upcoming maturity, or a change in ownership structure. But each event needs context. A recent deed recording may signal a buyer who still needs financing only in some cases. A recorded mortgage may point to a future refinance conversation, but it is not an invitation for an immediate rate-focused pitch.
The right contact window depends on the borrower’s likely stage, the product being offered, and the confidence of the underlying information. High-intent situations warrant fast, measured response. Lower-confidence signals should be enriched, prioritized, or monitored until a clearer reason to engage emerges.
1. Before a Known Financing Deadline
Deadlines create urgency. A loan maturity, balloon payment, adjustable-rate reset, construction draw requirement, or commercial refinance horizon can give lenders a defined reason to initiate a conversation. These moments are especially valuable because the borrower’s need is not theoretical.
The best outreach occurs far enough ahead to provide options, not just pressure. For commercial or investment borrowers, that may mean beginning the conversation months before maturity. For consumer lending, timelines vary by product, borrower readiness, market conditions, and applicable communication requirements.
The message should lead with planning rather than assumption. A lender does not need to claim that a borrower needs a loan. Instead, it can offer a review of available financing paths ahead of a known decision point. That distinction protects trust and produces a more productive conversation.
2. After a Property Event Changes the Financial Picture
Property events can reveal situations that deserve attention before they become obvious across the market. A purchase, transfer, inheritance-related filing, lien activity, entity formation, or portfolio acquisition may alter a borrower’s financing needs.
No single event should be treated as proof of intent. A deed transfer could be an arms-length sale, an estate action, a family transfer, or an internal entity change. The lender’s advantage comes from connecting the event to ownership history, property characteristics, existing debt, geographic focus, and likely borrower profile.
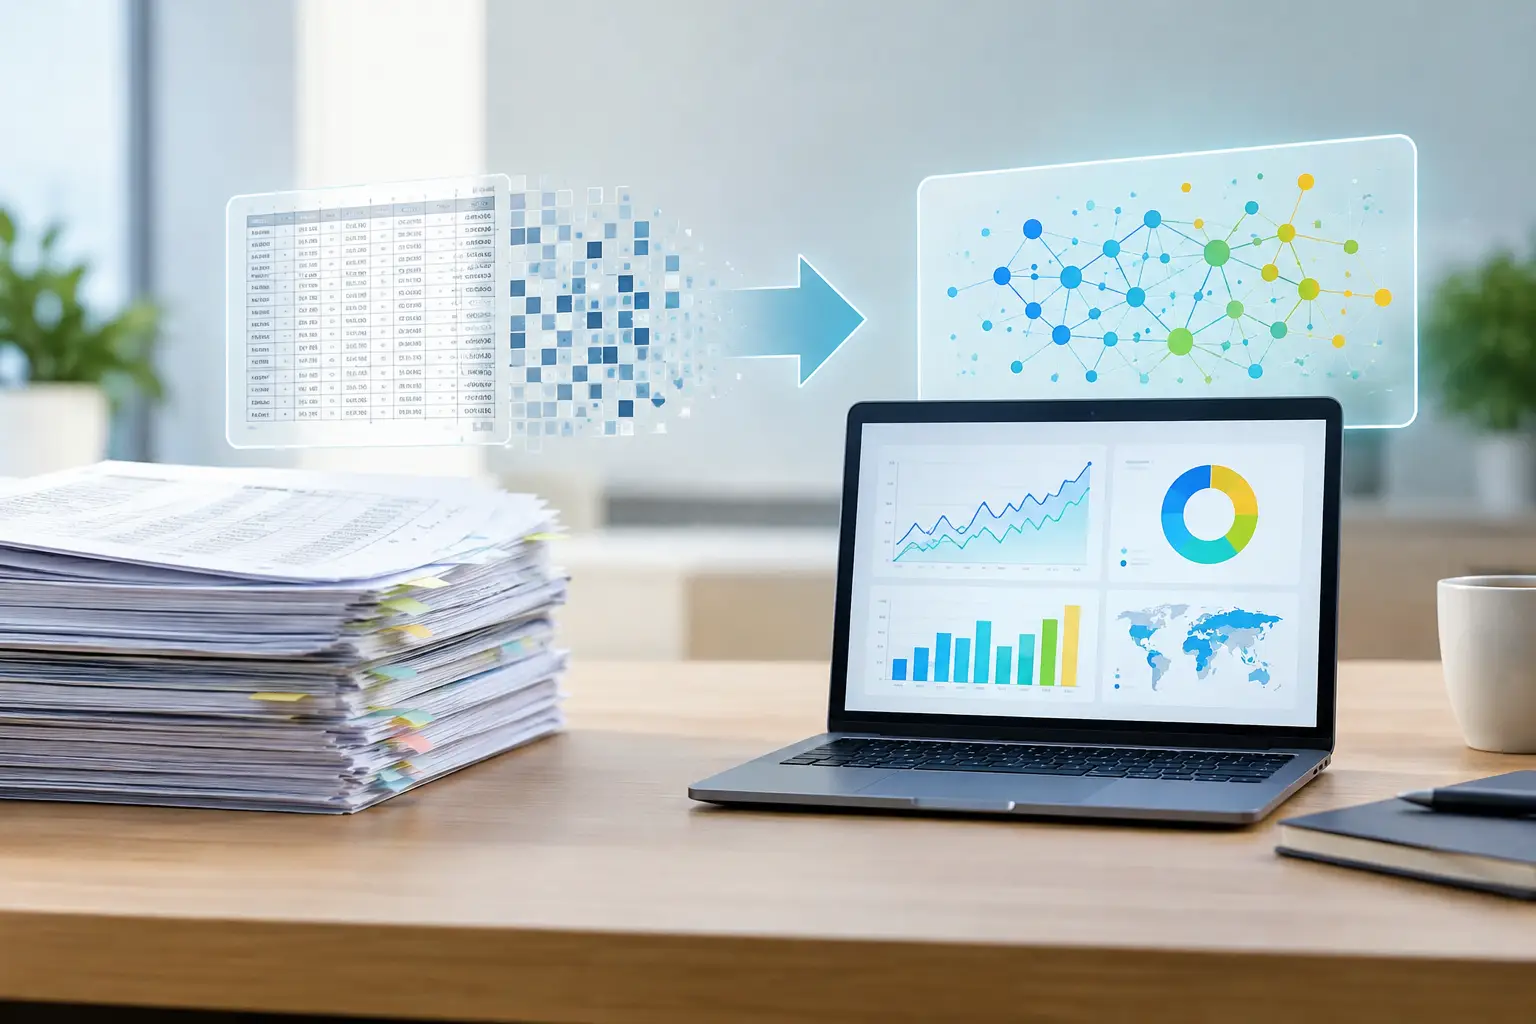
This is where opportunity intelligence improves on raw lead lists. Rather than calling every name attached to a record, teams can focus on the events that match their lending criteria. VORTOC’s model is built around this progression: identify the Deal Pulse, add Intelligence, then direct effort toward the Opportunity.
3. When Equity, Debt, or Market Conditions Create Options
Borrowers may not be actively shopping for financing, yet their position may have changed enough to justify a conversation. Rising equity, an improved credit profile, portfolio appreciation, debt payoff activity, or a meaningful shift in local market conditions can create new options.
The trade-off is sensitivity. A lender that presents a generic refinance pitch based on broad market movement may appear opportunistic. A lender that can explain a relevant scenario - such as consolidating investment-property debt, accessing capital for an acquisition, or evaluating a cash-out strategy - is more likely to earn attention.
These are planning conversations, not always immediate applications. For many borrowers, especially investors and owners with multiple properties, the value lies in understanding options before a transaction forces a rushed decision.
4. When Prior Engagement Shows Readiness
A borrower’s prior behavior is often more useful than a broad demographic filter. Previous application activity, a request for information, a completed prequalification, a rate-alert enrollment, or a past conversation can indicate a relationship worth revisiting.
Timing matters here as well. Following up immediately after an abandoned application may be appropriate if the borrower has requested assistance or consented to contact. Reaching out months later requires a new reason to be relevant. A material market change, a new product fit, or a known milestone can provide that reason.
Relationship data should be used carefully. Teams should maintain accurate records of contact preferences, opt-outs, prior outcomes, and channel permissions. A well-timed call that ignores a prior request not to be contacted is not an opportunity. It is a compliance and reputation risk.
5. When a Referral or Professional Network Creates Context
A referral from a real estate agent, financial advisor, attorney, builder, or property professional can make outreach more credible because it arrives with context. It also changes the conversation. The lender is not introducing a hypothetical offer to a cold audience. The lender is responding to an identified need or a trusted connection.
Even then, confirmation matters. Referral details can be incomplete, circumstances can change, and the borrower should never feel that their information has been passed around casually. A concise introduction, a clear reason for contact, and respect for the borrower’s preferred communication method are essential.
For lending teams, referral intelligence is most valuable when it is combined with independent property and market context. That allows the lender to prepare for the conversation without overreaching or relying on assumptions.
6. When the Signal Matches Your Actual Lending Box
Not every visible event deserves outreach. A lender focused on DSCR loans, multifamily financing, bridge debt, or owner-occupied residential mortgages should not pursue every record with a mortgage-related label. Volume without fit consumes staff time and lowers conversion quality.
Before contact, assess whether the prospect aligns with loan size, property type, geography, occupancy, credit profile, capital structure, and product availability. A narrower, prioritized audience often produces better outcomes than a larger unfiltered list.
This is also where speed needs discipline. Early identification creates a window, but rapid outreach to poorly qualified prospects can waste that window. The strongest teams establish a clear qualification threshold, then give loan officers the evidence behind the lead: what happened, why it matters, and what conversation may be appropriate.
7. Only After a Compliance Review Supports Contact
Publicly available information does not eliminate communication obligations. Before contacting a borrower or prospect, lenders should apply their organization’s policies and confirm that the intended channel, message, timing, and audience are permitted.
That may include screening against internal suppression lists and applicable do-not-call requirements, honoring opt-outs, validating consent where required, following company rules for calls and texts, and ensuring disclosures are accurate. Requirements can vary by channel, jurisdiction, product, and relationship. Legal and compliance teams should define the rules that govern each campaign.
Data accuracy is equally important. Public records can be delayed, incomplete, or attached to similarly named parties. Treat intelligence as a reason to investigate, not a reason to make unsupported claims. The first outreach should be framed as an invitation to discuss options, not a declaration about the borrower’s finances or intentions.
Build a Contact Strategy Around Relevance
The most effective lender outreach programs do not operate on a single trigger. They use a sequence: detect the event, verify the context, score the fit, select the compliant channel, and give the borrower a reason to respond.
That process creates a practical distinction between activity and opportunity. A newly recorded event may be interesting. A verified event connected to the right borrower, property, timing, and lending product is actionable.
Borrowers do not need more unsolicited messages. They need a lender who reaches out when the conversation can help them make a better decision. Find the event others overlook, then earn the right to act on it.