A loan officer can have thousands of contacts and still miss the borrower who is ready to act this week. That is the practical difference at the center of mortgage CRM versus lead platforms. One system helps a team manage relationships it already has. The other helps it recognize opportunity before it becomes obvious, then determine whether that opportunity deserves attention.
For mortgage lenders, the question is not which category is better. It is which part of the revenue process is underperforming. If follow-up is inconsistent, a CRM may be the immediate answer. If the pipeline lacks fresh, relevant opportunities or sales teams are sorting through weak lists, a lead platform may be the higher-leverage investment. The strongest operating model connects both.
Mortgage CRM versus lead platforms: the core difference
A mortgage CRM is primarily a relationship and workflow system. It stores contact records, tracks conversations, organizes tasks, manages milestones, and prompts follow-up. Its value grows after a prospect, referral partner, borrower, or past client enters the database.
A lead platform is primarily an opportunity-identification system. It looks outward, using data sources, behavioral indicators, property events, or market signals to identify people and situations that may warrant outreach. Its value begins before a prospect is known to the lender.
That distinction matters because many teams expect a CRM to solve a lead-generation problem. A CRM can automate a nurture sequence, assign a call task, and show which leads have gone cold. It cannot, by itself, identify the market event that created a new lending opportunity unless that information is being supplied from elsewhere.
The reverse is also true. A lead platform can surface a timely opportunity, but it is not designed to replace borrower communication history, loan-stage workflow, referral-source management, or long-term relationship nurturing. Finding the signal and converting the signal are different jobs.
Where a mortgage CRM earns its place
CRMs are essential when the lender’s main challenge is operational discipline. A team that receives inbound inquiries, referral partner introductions, open-house leads, database reactivation opportunities, and repeat-borrower business needs a dependable record of every interaction.
A well-run mortgage CRM helps originators answer basic but consequential questions: Who needs a call today? Which referral partners have not heard from us? Which applications are stalled? Which past clients are approaching an anniversary or may be candidates for a review?
This is where CRM automation earns its keep. The system can route inbound leads, create task sequences, send approved communications, and give managers visibility into activity levels and conversion stages. For branch leaders, it also creates accountability. The issue is rarely whether a loan officer believes follow-up matters. The issue is whether the business can see, measure, and improve it.
But a CRM’s view is usually limited to the records inside it. If the contact base is aging, poorly segmented, or filled with prospects who are not currently in market, better task management will not create enough new opportunity. It may simply make the team more efficient at working the same limited pool.
Where lead platforms create an advantage
Lead platforms address the discovery problem. They are built for teams that need to know what is changing in a market, which property-related events may create financing needs, and where sales effort should be allocated before competitors see the same opening.
The best platforms are not raw-data warehouses. Raw records can be plentiful and still be commercially weak. A filing, ownership change, listing movement, lien-related event, investor activity, or other public indicator does not automatically equal a qualified borrower. It is a starting point.
The advantage comes from context and prioritization. A meaningful platform organizes fragmented events, enriches the underlying records, analyzes relevance, and directs the user toward the opportunities most likely to justify action. That reduces the time loan officers spend treating every record as equally valuable.
For mortgage teams, this may mean identifying prospects connected to changes that suggest a refinance conversation, purchase financing need, investor strategy shift, equity-related discussion, or referral opportunity. The exact use case depends on the lender’s market, product mix, licensing footprint, and outreach strategy. The principle is consistent: timing improves when the team sees meaningful activity early.
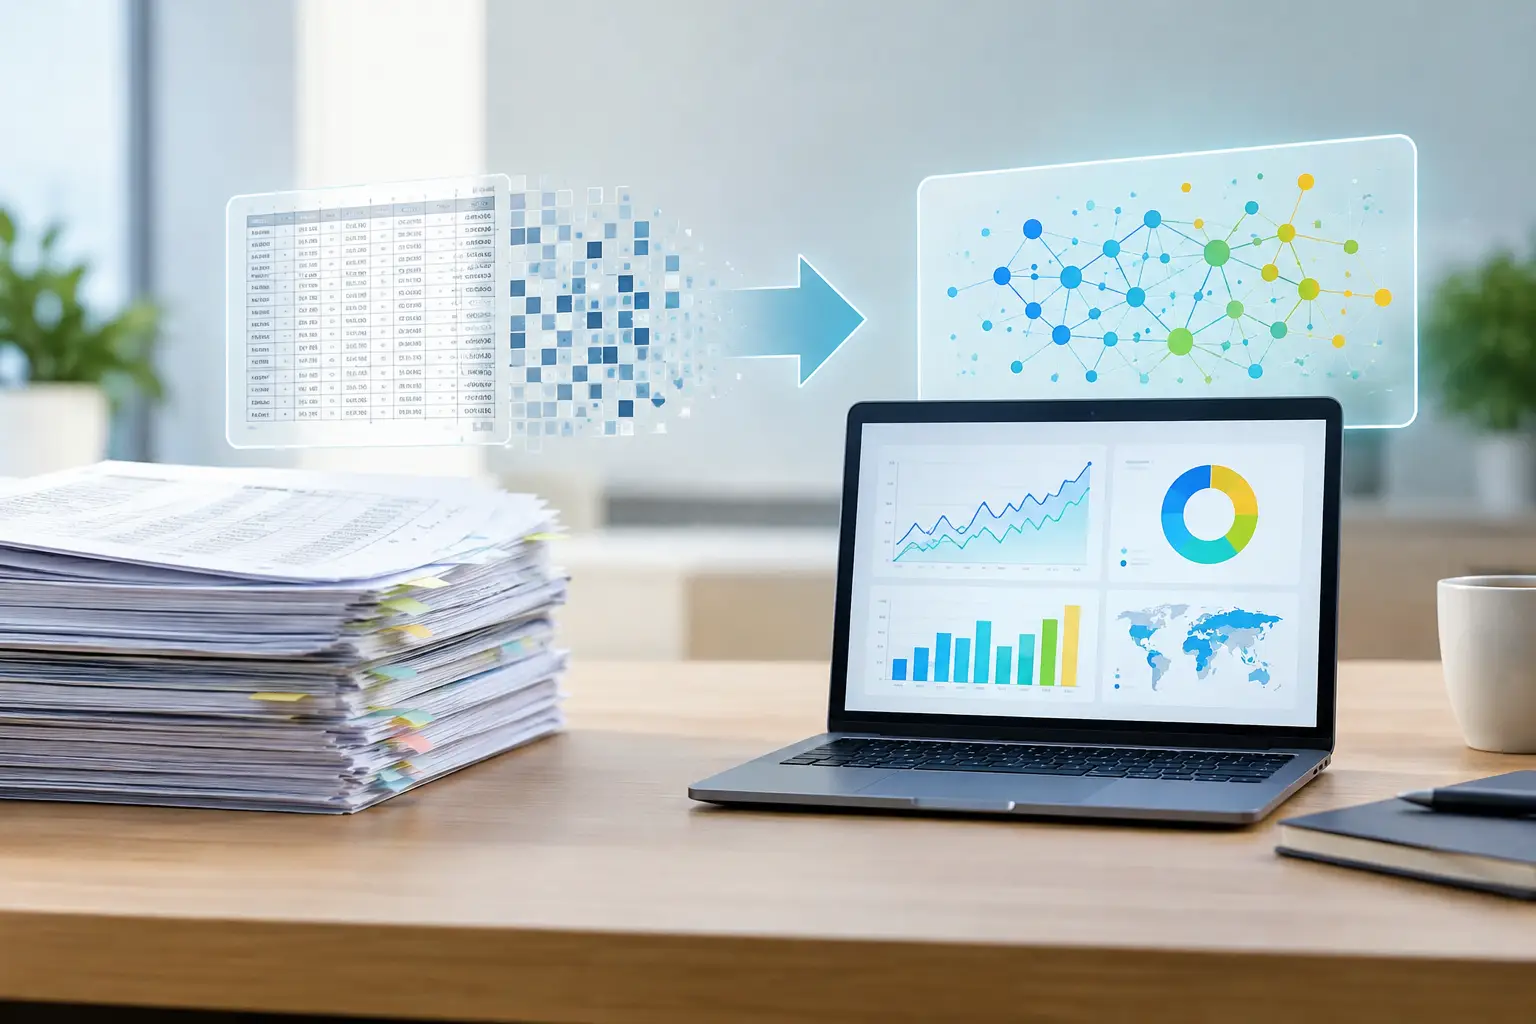
VORTOC frames this progression clearly: Deal Pulse, Intelligence, and Opportunity. First, an event is detected. Next, it is given context. Then, it becomes a prioritized reason to act. That is materially different from receiving another broad lead list with little explanation of why a contact belongs at the top of the call queue.
The trade-off: volume versus relevance
Not every lead platform produces better leads. Some deliver scale without enough filtering. They may provide names, phone numbers, and property attributes, yet leave the sales team to decide which records matter. That can create a familiar problem: more records, more cost, and more wasted calls.
Likewise, not every CRM implementation improves conversion. A system full of incomplete records and neglected tasks becomes an expensive address book. Automation can amplify a weak process as easily as a strong one.
The real comparison is not CRM against platform. It is workflow depth against market intelligence. A CRM is usually stronger at managing known relationships across time. An intelligence-led lead platform is usually stronger at identifying unknown or overlooked opportunities at the right moment.
For a solo originator with a deep referral network, CRM discipline may produce the fastest return. For a growth-minded lender entering new territories, rebuilding a thin pipeline, or seeking a sharper edge in competitive markets, prioritized opportunity intelligence may be the larger gap.
How the two systems should work together
The most effective mortgage operations use a lead platform as the front end of opportunity discovery and the CRM as the operating system for pursuit. The lead platform answers, “What should we look at now?” The CRM answers, “What did we do about it, and what happens next?”
That handoff should be deliberate. Only opportunities that meet a defined threshold should enter the CRM as active records. Otherwise, the system becomes crowded with speculative data and the sales team loses confidence in the queue.
A practical handoff includes the reason the opportunity was identified, relevant property or market context, source and date of the signal, ownership or contact information where lawfully available, and the recommended next action. The loan officer should not have to reconstruct the case from disconnected records before deciding whether to call.
Once in the CRM, the opportunity needs a clear workflow. Assign an owner, set a first-action deadline, establish approved outreach steps, and record the outcome. Over time, that feedback should refine how the business defines a high-value signal. The goal is not simply more activity. It is better allocation of activity.
Questions to ask before choosing
Before adding either system, mortgage leaders should examine the bottleneck honestly. Is the team failing to respond to leads? Is it unable to generate enough relevant opportunities? Are originators spending too much time researching fragmented public records? Are managers unable to see what happens after a lead is assigned?
Then assess the quality of the current database. If contact history is incomplete and follow-up is inconsistent, start by fixing CRM process and ownership. If the workflow is sound but the top of the funnel is weak, look for a platform that provides timely, contextual, prioritized signals rather than undifferentiated volume.
Integration deserves attention, but it should not dominate the decision. A perfect technical connection has little value if the incoming opportunities are not actionable. Conversely, a high-quality opportunity source can justify a disciplined manual process while the team validates fit and proves economics.
Compliance is equally central. Public-record information, consumer contact data, and marketing activity carry legal and policy obligations. Teams should establish permissible-use standards, honor applicable contact preferences and regulations, validate data where needed, and train users on lawful outreach. Intelligence improves decisions; it does not remove the lender’s responsibility to use information appropriately.
Build the system around the moment of action
The mortgage business rewards relevance, responsiveness, and timing. A CRM protects the relationship once it exists. A lead platform helps reveal the event that makes a relationship worth starting.
Treating those roles as interchangeable leads to poor buying decisions and crowded pipelines. Treating them as connected layers creates a more disciplined growth engine: detect what others overlook, understand why it matters, and give the right person a reason to act while the opportunity is still timely.