A refinance opportunity rarely announces itself as a refinance opportunity. It appears first as a recorded event, a change in property status, a loan-age pattern, or a financial condition that suggests a borrower may be ready to act. Teams that know how to identify refinancing opportunities turn those disconnected signals into a focused pipeline before competitors are working from the same obvious list.
For mortgage lenders, real estate professionals, and investment teams, the advantage is not access to more records. It is the ability to distinguish meaningful movement from background noise, apply context, and direct attention toward the situations most likely to warrant outreach.
How to Identify Refinancing Opportunities Before They Become Obvious
Refinancing is driven by a combination of economics, borrower circumstances, property conditions, and timing. A lower market rate may create broad demand, but rate movement alone does not identify the households or properties most likely to transact. The real opportunity lies in finding the overlap between a relevant market condition and a specific borrower or property signal.
Start with recorded loan and ownership activity. A mortgage recorded several years ago may indicate a borrower who is approaching a point where rate savings, changed equity, or a revised loan structure could be worth evaluating. The age of the existing loan matters, but it is not sufficient on its own. A recent purchase, refinance, or ownership transfer may make an immediate refinance less likely, while a longer-held loan combined with rising property value can create a stronger potential case.
Equity is another useful indicator. When property values rise, owners may have options that were unavailable at origination: removing mortgage insurance, consolidating higher-cost debt, funding renovations, or restructuring an investment property loan. Estimated equity should be treated as a prioritization signal, not a promise of qualification. A strong opportunity model accounts for recorded debt, property characteristics, ownership tenure, and local value trends while recognizing that the borrower’s income, credit profile, and current objectives remain unknown until a compliant conversation occurs.
Property events can add urgency. A transfer into a trust, a change in ownership structure, a divorce-related filing, a death notice, an inherited property, or a recently completed renovation may alter how an owner thinks about financing. These events do not automatically mean a borrower needs a new loan. They create context. Context helps a team determine whether the situation deserves timely, relevant outreach or should remain a lower-priority watch signal.
Build a Signal Model, Not a Generic Refinance List
Raw public records can produce volume quickly. Volume is not the same as opportunity. A list of every owner with an older mortgage often contains borrowers with no economic incentive, properties that do not fit the lender’s program, duplicate records, inactive contact data, and situations where outreach would be poorly timed.
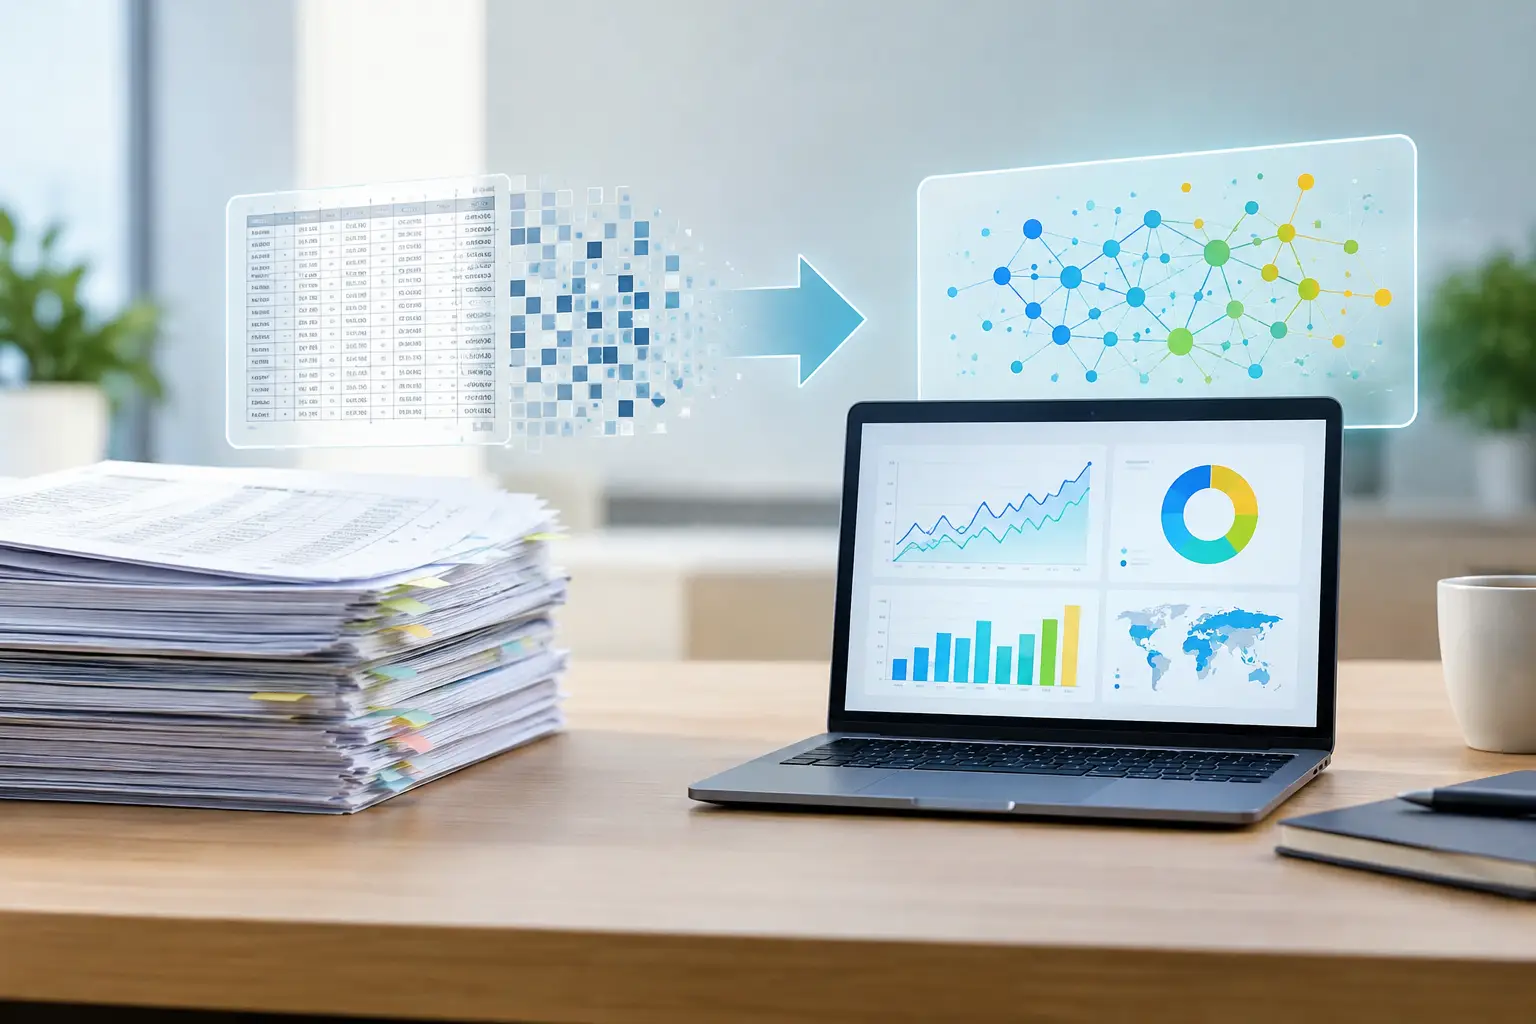
A better approach organizes signals into three stages: Deal Pulse, Intelligence, and Opportunity.
Deal Pulse: Capture the events that indicate change
Deal Pulse is the first indication that something has changed. For refinance workflows, it can include newly recorded deeds of trust, satisfactions, assignments, ownership transfers, tax or lien events, property improvements, and shifts in local market conditions. The objective is not to contact everyone associated with an event. It is to create a current view of market movement.
Timing matters here. A signal that reaches a team weeks after it is recorded may still be useful, but it is less likely to create an information advantage. Early detection gives loan officers and acquisition teams time to evaluate the event before it becomes another broadly marketed lead category.
Intelligence: Add the context that determines relevance
The next step is interpretation. Pair the event with loan age, estimated equity position, property type, ownership tenure, geography, transaction history, and any other lawful data attributes that help explain the situation.
For example, a homeowner with a mortgage originated during a higher-rate period may appear attractive at first glance. The opportunity becomes more credible if the property has appreciated, the owner has remained in place long enough to build equity, and the current lending environment supports a meaningful benefit. Conversely, a similar borrower may be a poor priority if recorded activity suggests a recent refinance, a pending sale, or a loan balance that leaves limited room for the intended program.
This is where many teams lose time. They ask staff to manually research records one by one, then rely on individual judgment to decide who receives a call. That process can work at small volume. It breaks down when the market changes quickly or when several territories must be monitored at once.
Opportunity: Prioritize the next best action
An opportunity is not just a signal with a phone number attached. It is a situation ranked according to commercial relevance and readiness for action. Prioritization should reflect the team’s actual lending strategy: owner-occupied conventional loans, cash-out refinance scenarios, investor portfolios, jumbo borrowers, second liens, or another defined segment.
A practical score can weigh several factors together. Loan age, estimated available equity, property value band, local rate sensitivity, ownership changes, and recency of recorded events can each contribute to a higher or lower rank. The precise formula depends on the business model. A retail lender may favor likely rate-and-term borrowers, while an investor-focused lender may place more weight on rental property ownership, portfolio concentration, and equity extraction potential.
The key is to make the ranking explainable. Revenue teams need to understand why a record is prioritized so they can tailor outreach and improve the model over time. A black-box score with no operational meaning creates skepticism. A clear score tied to observable conditions creates action.
Look for Trigger Combinations, Not Single Events
The most reliable refinance prospects are often identified through combinations of indicators. A single recorded mortgage from several years ago is weak evidence. That same mortgage, combined with meaningful property appreciation and a current rate environment that improves the borrower’s options, is materially more relevant.
Consider an owner who bought a home when rates were elevated, has held it long enough for local appreciation to build equity, and recently recorded a permit for a major renovation. The permit does not prove a refinance need. It may, however, suggest a financing conversation could be timely, especially when the owner’s estimated loan profile supports a cash-out or renovation-related scenario.
The inverse is equally valuable. Signals that reduce relevance should suppress outreach. Recent loan recordings, a recorded sale listing indicator, a satisfaction suggesting a paid-off mortgage, or a property type outside the team’s target programs may move a record out of the active queue. Better exclusion logic protects sales capacity and reduces irrelevant contact.
Turn Intelligence Into a Refinance Outreach Workflow
A prioritized signal is only valuable when it reaches the right person with enough context to act. Assign ownership based on geography, loan type, account history, or relationship status. Then give the assigned professional a concise reason for the outreach, not a data dump.
The message should lead with potential value rather than an assumption. A borrower may be open to reviewing payment structure, equity access, mortgage insurance removal, or investment-property financing. They may also have no interest at all. The role of the signal is to make the outreach more relevant, not to presume a financial need or make an unsupported claim.
Establish clear response windows. High-priority events should be reviewed quickly, while lower-confidence records can enter a nurture process or remain under observation until additional signals appear. Capture outcomes from every outreach attempt: contacted, not interested, recently refinanced, insufficient benefit, follow up later, or closed. These outcomes improve future prioritization because they show which signal combinations actually convert.
VORTOC is built around this progression from fragmented event data to contextual intelligence and prioritized opportunity. The goal is not to hand teams another broad list. It is to help them find the events others overlook and focus resources where market movement is most likely to matter.
Keep Refinance Intelligence Grounded in Compliance
Public-record intelligence does not remove the need for disciplined compliance. Teams remain responsible for lawful use of data, consumer-contact practices, licensing requirements, fair lending obligations, privacy rules, and internal policies. A signal can support prospecting and prioritization, but it should never become the basis for an inaccurate statement about a consumer’s finances, eligibility, or personal circumstances.
Maintain suppression processes, respect contact preferences, and ensure that marketing and calling workflows follow applicable federal, state, and local requirements. Treat estimated values, inferred loan scenarios, and life-event indicators as internal decision support. Verify material information through appropriate customer conversations and underwriting processes.
The strongest refinance pipeline is not built by calling more names. It is built by recognizing meaningful change early, understanding what that change may indicate, and giving each prospect the level of attention the situation actually merits.